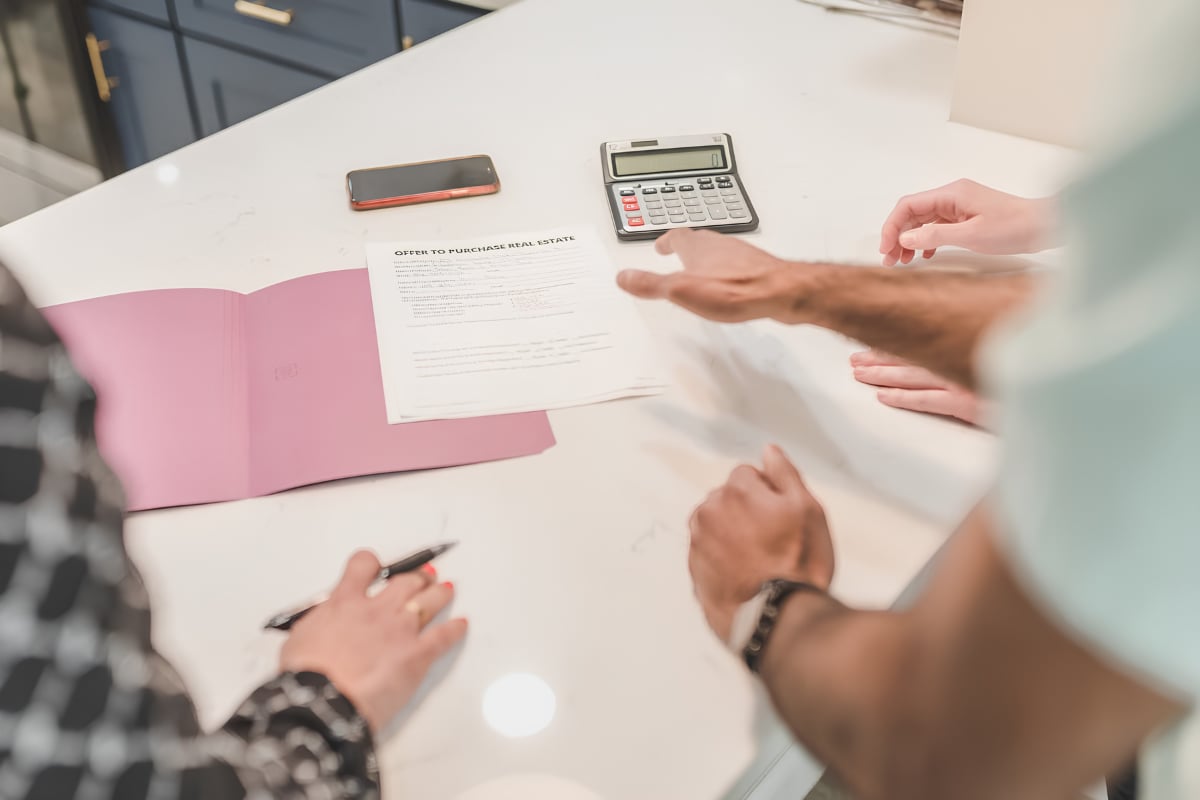
When buyers talk about negotiating on a home, the first thing they usually think about is price.
I understand why.
If a home is listed at $1.2 million, it’s natural to focus on how much lower the seller might go.
But with mortgage rates still high, I think buyers should be looking at a bigger picture.
Sometimes the better question is:
“What terms would make this home more comfortable for me to own?”
Mortgage Rates Are Still Affecting Monthly Payments
Freddie Mac reported the average 30-year fixed mortgage rate at 7.40% as of October 15. Freddie Mac
That means even a relatively small change in financing can make a meaningful difference in the monthly payment.
This is why I don’t like looking at purchase price by itself.
A buyer may negotiate a lower price, but another option could be asking for help with closing costs or using funds toward an interest-rate buydown, depending on the loan and what the seller is willing to consider.
What Is a Seller Credit?
A seller credit is an amount the seller agrees to contribute toward certain buyer costs at closing.
According to the Consumer Financial Protection Bureau, seller credits can sometimes be negotiated toward closing costs, depending on the contract and the loan involved. Consumer Financial Protection Bureau
Those costs may include things like:
- Certain lender fees
- Appraisal costs
- Title-related costs
- Prepaid expenses
- Other eligible closing expenses
The exact amount and what it can be used for depend on the loan program and lender requirements.
That’s why I always want the lender involved before deciding what kind of credit to request.
What About Buying Down the Interest Rate?
Another option buyers sometimes hear about is paying discount points.
The CFPB explains that points are paid upfront in exchange for a lower mortgage rate. One point equals 1% of the loan amount, although the actual rate reduction varies by lender and market conditions. Consumer Financial Protection Bureau
For some buyers, using funds toward the interest rate can have a bigger effect on the monthly payment than using the same amount to reduce the purchase price.
But that doesn’t mean points are always the better choice.
It depends on:
- How long you expect to keep the loan
- How much cash you want to keep available
- The actual rate reduction being offered
- Your overall monthly budget
- Whether you may refinance later
I’d want the lender to run the numbers both ways before making that decision.
Why I Think This Conversation Makes Sense in Burbank Right Now
Burbank is still competitive, but the market isn’t behaving the same way for every property.
Redfin’s September data shows homes selling at about 99.4% of their list price on average, while approximately 24.7% of listings had a price drop. Redfin
To me, that means there may be situations where a seller is open to discussing terms, especially if a home has been sitting longer or has already adjusted its price.
That doesn’t mean every seller will agree to credits.
It also doesn’t mean buyers should automatically ask for everything.
I’d rather look at the individual property and figure out which request actually helps the buyer most.
A Lower Price and a Better Payment Aren’t Always the Same Thing
This is the part I think buyers sometimes miss.
Imagine a seller is willing to give a little.
You might have several ways to structure that negotiation:
- Reduce the purchase price
- Ask for closing-cost assistance
- Use a credit toward eligible financing costs
- Adjust another term of the offer
The option that looks best on paper isn’t always the one that helps your monthly budget most.
That’s why I like to ask:
What problem are we actually trying to solve?
If the issue is cash needed at closing, a credit may be useful.
If the issue is monthly affordability, financing options may matter more.
If the home simply isn’t worth the asking price based on comparable sales, then price may still be the main conversation.
Sellers Should Think About This Too
I think this matters for sellers as much as buyers.
A seller may receive an offer that isn’t quite at the number they hoped for, but the structure of that offer matters.
Sometimes a buyer may be willing to stay closer to the asking price if the seller contributes toward certain closing costs.
Depending on the situation, that could be worth comparing with a straight price reduction.
There are also loan-program limits on how much a seller can contribute. For example, Fannie Mae sets maximum financing concessions based on occupancy and loan-to-value ratio. Fannie Mae Selling Guide
So again, this needs to be coordinated with the buyer’s lender.
I’d Look at the Whole Offer
If I were buying in Burbank right now, I wouldn’t focus on only one number.
I’d look at:
- The price compared with recent sales
- My estimated monthly payment
- Cash needed at closing
- Potential seller credits
- Financing options from my lender
- The property’s condition and expected expenses
That gives you a much better picture of whether the home actually fits.
The Best Negotiation Is the One That Helps Your Situation
There isn’t one negotiation strategy I’d use for every buyer.
Some buyers need to protect their cash.
Some care most about the monthly payment.
Others may be comfortable with the financing but want to make sure they aren’t overpaying for the property.
The important part is knowing what matters most before you start negotiating.
That way, we’re not just asking for a lower price because that sounds like the obvious thing to do.
We’re structuring the offer around what actually helps you.
Frequently Asked Questions
Can a seller pay all of my closing costs?
Not always. The amount a seller can contribute depends on the loan program, the buyer’s costs, and other financing requirements. Your lender can tell you the limit that applies to your loan. Fannie Mae Selling Guide
Is a seller credit the same as a price reduction?
No. A price reduction lowers the purchase price. A seller credit generally goes toward eligible costs at closing.
Does paying discount points always make sense?
No. Points cost more upfront in exchange for a lower rate, so whether they make sense depends on how long you expect to keep the loan and the actual savings offered. Consumer Financial Protection Bureau
Are Burbank sellers negotiating right now?
It depends on the property. Redfin’s September data shows Burbank homes selling around 99.4% of list price on average, while 24.7% of listings had price reductions. That suggests some room for negotiation exists, but every home and seller situation is different. Redfin
Looking at a Burbank Home?
If you’re considering a purchase, I’m happy to help you look beyond the asking price and think through the full offer.
Sometimes the right structure can make just as much difference as the number at the top of the contract.
Becky Richards
REALTOR® | Equity Union
CA DRE #01767305
(818) 515-8685
[email protected]
BeckySellsLA.com